Summary
A Calgary household earning $120,000 can generally qualify for somewhere around $539,000 right now, which is just shy of what a typical home here costs. Drop to $85,000 and you’re closer to $376,000, which is condo and townhouse territory. What decides it isn’t really your salary, though. It’s the stress test rate, your down payment, and whatever else you’re already paying every month.
Most people do this backwards.
They find a house, fall for it, then try to make the numbers fit around it. The better order is working out what you can comfortably carry, then going looking.
Here’s how lenders actually decide, with Calgary numbers as of October 2026.
Lenders Do Not Use the Rate You Will Actually Pay
This one catches almost everybody.
The best five-year fixed rate on an insured mortgage is sitting near 4.34 per cent. That’s the rate you’d pay.
It is not the rate you get tested at.
Under the federal stress test, a lender has to qualify you at whichever is higher: 5.25 per cent, or your contract rate plus two percentage points. Right now that works out to 6.34 per cent.
The payment they measure you against is roughly 21 per cent larger than the one you’d actually be making. That gap is the single biggest reason people get approved for less than they were expecting.
What You Actually Need as a Down Payment
Less than most people assume, at Calgary prices.
The rules are tiered. Five per cent on the first $500,000, ten per cent on anything between $500,000 and $1.5 million, and twenty per cent on anything above that. So on a $566,700 purchase, the minimum comes to about $31,670. For an apartment condo at $291,400, it’s $14,570.
Anything under twenty per cent down means mortgage default insurance. With five per cent down, that premium is four per cent of the loan, and it gets added to your balance rather than paid at closing.
The Two Ratios That Decide Everything
Lenders run two numbers on you.
GDS, or gross debt service, is your housing cost against your gross income. The mortgage payment at the stress-test rate, property tax, a heating estimate, and half your condo fees. The ceiling on an insured mortgage is 39 per cent. TDS, total debt service, is all of that plus every other monthly obligation. Car loans, student loans, three per cent of your credit card balances, three per cent of your line of credit limit whether you’ve touched it or not. The ceiling there is 44 per cent.
Whichever one you hit first becomes your real limit.
What Different Calgary Incomes Buy Right Now
Running those rules at current pricing, on a twenty-five year amortization with no other debt in the picture:
A household earning $85,000
Roughly $376,000. That’s apartment condos comfortably, some row housing, and not a great deal else.
A household earning $120,000
Roughly $539,000. Close to a typical Calgary home without quite reaching it.
A household earning $150,000
Roughly $684,000, which puts detached housing on the table across most of the city.
Notice the jumps run slightly ahead of the income gaps. Fixed costs like the heating allowance don’t scale with your salary, so each extra dollar you earn buys a little more house than the last one did.
These are illustrative rather than pre-approvals. Your credit score, your actual down payment and the specific property all move them around.
What the Typical Calgary Home Actually Demands
Now flip it the other way.
CREB put the September benchmark at $566,700. Carrying that with the minimum down payment takes a household income somewhere near $126,000.
Condo buyers have an easier time of it. Allowing for fees, a $291,400 apartment needs closer to $73,000.
A row house at $412,400 sits around $97,000.
Calgary’s median individual income is roughly $45,400. Which is a fairly blunt explanation for why the detached market here runs almost entirely on two incomes, and why household income rather than salary is the number that matters.
Property Tax and Condo Fees Come Out First
These aren’t afterthoughts in the calculation. They sit inside it.
Calgary’s residential mill rate works out to about 0.665 per cent. On a $566,700 home that’s roughly $3,770 a year, or $314 a month, and it counts in full against your GDS.
Condo fees count at half. Calgary fees average somewhere around fifty cents per square foot, so a thousand-square-foot unit runs about $500 a month, and $250 of that quietly eats into what you can borrow.
A condo with high fees can cost you more buying power than spending the same money on a higher purchase price would have.
Your Car Payment Is Expensive Twice
Here’s the one that genuinely surprises people.
A $500 monthly car payment, on an $85,000 household income, drops your maximum purchase price by roughly $20,600.
Not $500. Twenty thousand dollars of house.
Worth sitting with before you sign anything at a dealership.
The same payment at $120,000 or $150,000 barely moves anything, because at those incomes GDS runs out before TDS does. Debt punishes lower incomes disproportionately in this particular calculation.
If buying is on the horizon in the next year or so, that’s worth knowing before you finance a vehicle. It’s also worth weighing against what else that money could be doing.
Thirty Years Instead of Twenty-Five
The amortization rules changed, and plenty of people haven’t caught up yet.
First-time buyers can now take a thirty-year amortization on an insured purchase, new build or resale. Any buyer can take thirty years on a newly built home.
At $120,000 of household income, that moves the ceiling from about $539,000 to about $575,000. At $150,000, from $684,000 to roughly $729,000.
It costs a 0.20 per cent bump on the insurance premium, and a meaningful amount of extra interest over the life of the loan.
More house now, more cost later. That’s the trade, stated plainly.
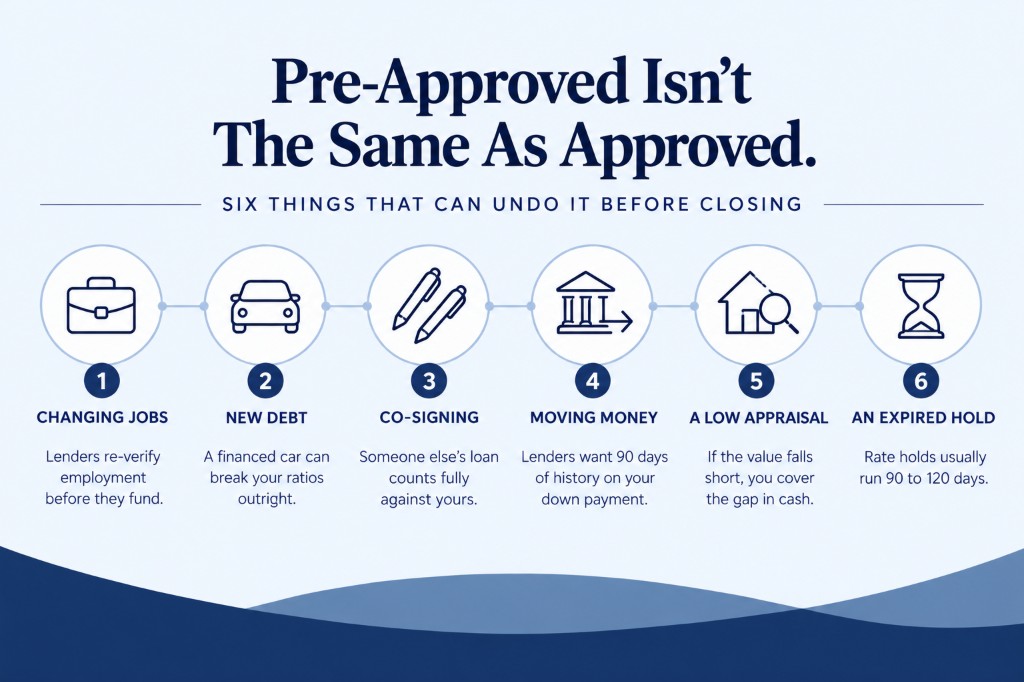
Qualifying For It and Affording It Are Different Questions
A lender will tell you your maximum. They won’t tell you whether it’s a good idea.
Nothing in the GDS and TDS calculation knows about daycare, or what you were hoping to put into an RRSP this year, or the fact that your roof is fifteen years old.
Plenty of people buy right at their ceiling and spend the next five years feeling it. That gap between what a lender allows and what a household can actually absorb is a big part of whether Calgary feels affordable to you.
The more useful exercise runs the other direction. Decide the monthly payment you’re actually comfortable with, then work backwards to a price. It lands on a smaller number almost every time, and a considerably easier decade.
Before You Call a Lender
Three things worth doing first.
Pull your own credit report, because the rate you get quoted depends on it and unpleasant surprises are common.
Add up every fixed monthly obligation, including the credit card you clear in full each month, because the lender counts three per cent of that balance either way.
And settle on what you want the payment to be before you find out what it could be. Those are very different numbers, and only one of them is yours.
Frequently Asked Questions
How much income do you need to buy a house in Calgary?
Depends what you’re buying. A typical Calgary home at September’s $566,700 benchmark takes around $126,000 of household income with the minimum down, while a row house near $412,400 needs roughly $97,000 and an apartment condo at $291,400 comes in closer to $73,000 once condo fees are counted.
What is the minimum down payment in Calgary?
The tiers are federal, so Calgary is no different from anywhere else. Five per cent on the first $500,000. Ten per cent on any portion between $500,000 and $1.5 million. On a $566,700 home that lands at roughly $31,670.
What rate does the mortgage stress test use in 2026?
Whichever is higher, 5.25 per cent or your contract rate plus two points. With insured five-year fixed rates near 4.34 per cent, that puts the qualifying rate around 6.34. The practical effect is being tested on a payment about 21 per cent bigger than the one you would actually make.
How much does a car payment reduce what I can borrow?
More than you would think. A $500 monthly payment on an $85,000 household income knocks roughly $20,600 off the maximum price. It happens because the payment pushes your total debt service ratio to its ceiling before the housing ratio gets anywhere near its own. Push the income to $120,000 or $150,000 and the same payment barely registers. Debt hits lower incomes much harder in this particular calculation.
Can I still get a thirty-year amortization in Canada?
Yes, in two situations: first-time buyers on any insured purchase, new build or resale, and any buyer at all on a newly built home. It costs 0.20 per cent on the insurance premium and a meaningful amount of extra interest across the full term.
Do condo fees affect how much mortgage I qualify for?
They do, at half their value. Lenders fold fifty per cent of your monthly fees into the gross debt service calculation. Calgary averages somewhere around fifty cents per square foot, so a thousand-square-foot unit runs about $500 a month. That puts $250 against your ratios before anything else is even considered.